Construction Loans
Construction loans work differently to a standard home loan, with your loan funds released progressively as your builder completes each stage of construction. Rather than paying interest on the entire approved loan from day one, you’ll only pay interest on the amount that has been released.
During your construction, we help you navigate progress payments, valuations, lender requirements and your available funds throughout the build, while structuring the loan around your construction contract and overall project.
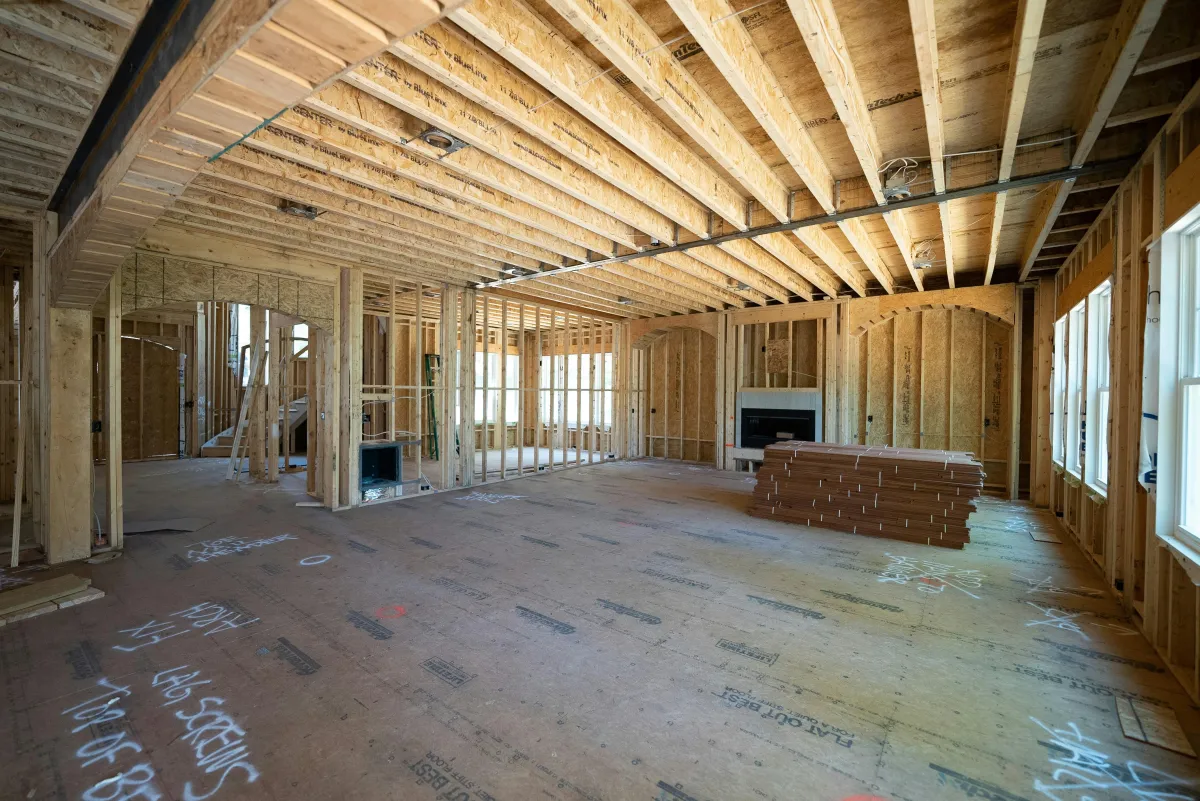
Building a New Home or Investment Property?
Find out exactly how much you can borrow and what funds you'll need to contribute.
Understand how progress payments work as your build moves through each construction stage.
Compare construction loan options across a range of lenders.
Get your finance organised around your building contract, land and overall project costs.
Completing a Knockdown-Rebuild or adding a Granny Flat?
Understand how your existing property, land value and current lending impact your options.
Find out how much you can borrow towards demolition and construction costs.
Learn about valuations, progress payments and lender requirements.
Compare your lender options and structure your finance around the entire project.
Frequently Asked Questions
How does a construction loan work?
A construction loan is generally released progressively as your build moves through different stages, rather than providing the full loan amount upfront. Your lender makes progress payments to the builder as each agreed construction stage is completed.
How much deposit do I need for a construction loan?
The amount you need will depend on the total land and construction costs, your existing equity or available funds, and the lender's requirements. We can assess the complete project to determine how much you may be able to borrow and what contribution you'll need.
What are progress payments?
Progress payments are payments made to your builder as construction reaches specific stages. These commonly include deposit, base/slab, frame, lock-up, fixing and completion stages, although the exact schedule will depend on your building contract.
Do I pay repayments on the entire construction loan from the beginning?
Generally, no. During construction, interest is typically calculated on the amount of the loan that has actually been drawn down rather than the entire approved construction loan. Your repayments therefore generally increase as more funds are released throughout the build.
Can I get a construction loan for a knockdown rebuild?
Yes. Construction finance can potentially be used to demolish an existing property and build a new home. The lender will assess factors including your existing property and loan, land value, demolition and construction costs, building contract and the expected value of the completed property.
Can I get a construction loan for an investment property?
Yes. Construction loans can be used for both owner-occupied homes and investment properties. For an investment build, lenders may also consider factors such as expected rental income when assessing your application.
How does the lender value a property that hasn't been built yet?
The lender will generally arrange an “as if complete” valuation using your land, building contract, plans and specifications. This estimates what the property is expected to be worth once construction has been completed.
What happens if my building costs increase during construction?
With a Fixed Price Building Contract, variations need to be requested and approved. Variations generally are not covered by your approved construction loan. Depending on the circumstances, you may need to contribute additional funds yourself or have further borrowing assessed and approved by the lender. It's important to allow for some unexpected costs when planning your build, in case materials included in your contract are not available, or for any unforeseen hinderances during the build.
What documents do I need for a construction loan?
In addition to the usual income and financial documents required for a home loan, lenders will generally require documents relating to the build, such as your signed building contract, plans, specifications and progress payment schedule. Additional documents may be required depending on the project and lender.
Can I get construction finance to build a duplex or complete a property development?
Yes. We can assist with finance for projects such as building a duplex or multiple dwellings on an existing or newly purchased block of land. Depending on the size and nature of the project, this may be financed through a standard construction loan or require specialist development finance. We can assess the project, expected costs, end values and your financial position to determine which lending options may be suitable.